In 2026, Myanmar’s local pharmaceutical production narrative is closely tied to how demand is shifting and how reliably manufacturers can source inputs. A clear signal comes from consumer behavior. Euromonitor estimated Myanmar’s consumer health market at approximately 451.3 billion kyats (US$107 million) in 2025, and it noted that vitamins and dietary supplements accounted for the largest share. The same reporting describes pharmacies as the primary pharmaceutical distribution channel in the country as self-medication and preventive healthcare become more common. For local manufacturers, these shifts can influence which products to prioritize and which distribution channels to support as import substitution discussions evolve.
Import substitution is not only a question of what Myanmar uses, but also how the value chain is organized. IndexBox frames the pharmaceutical-related chain through value-chain positions that include API manufacturing, pharmaceutical formulation, sterilization and filling, packaging and labeling, and distribution to hospitals and pharmacies, within a statistical framework using HS 382490 for “products and preparations for pharmaceutical or surgical uses.” In its Myanmar coverage, IndexBox reports that, in 2025, Myanmar’s other chemical products market was finally on the rise to reach $X for the first time since 2015, ending an eight-year declining trend. At the same time, it notes that consumption peaked at $X in 2015 and did not regain momentum from 2016 to 2025. For local production plans, that pattern emphasizes the need to align substitution ambitions with realistic supply capability and demand signals.
Where Import Substitution Gets Stuck: Packaging, Utilities, and Traceability
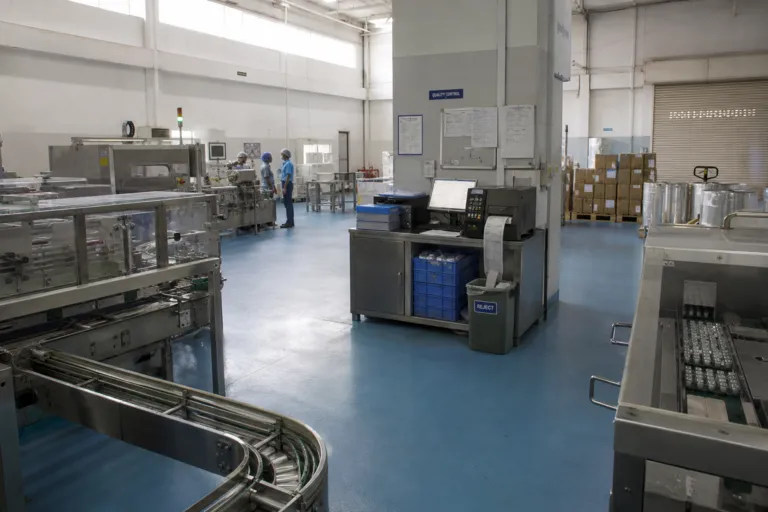
Production scale-up often bottlenecks outside the tablet press. MarkWide Research places the Myanmar packaging market at $1.8 billion in 2026, forecast to reach $3.81 billion by 2035, progressing at an 8.70% CAGR across the period. Yet the same source flags constraints that matter to pharmaceutical packaging, including “resin import dependency,” where licensing delays for pre-used plastic resin create raw material volatility for rigid plastics converters serving personal-care and pharmaceutical bottle segments. It also points to utility capacity bottlenecks: unreliable electricity supply in Thanlyin industrial zone can constrain blown film extrusion uptime, pushing converters toward diesel generator backup at elevated operating cost. Even where rigid packaging exists, MarkWide notes that medical-grade resin purity requirements can limit domestic feedstock substitution, which can keep packaging inputs tied to imports.
As local production expands, so does the need for supply-chain control and packaging-level compliance. 6Wresearch outlines Myanmar’s pharma serialization market through solution categories such as track-and-trace software, barcode printing systems, serialization hardware, and regulatory compliance, and it maps technology options including blockchain/cloud, 2D/QR coding, optical scanners, and AI validation tools. While the source text provided does not state market-size figures, the segmentation itself signals the operational building blocks a local producer may need to compete with imports on credibility, verification, and distribution integrity. This becomes especially relevant as pharmacies are described as the country’s primary distribution channel, which can increase the number of nodes where product authentication matters.
In parallel, product mix matters for domestic formulation strategy. 6Wresearch segments Myanmar’s prescription drug market by product types such as cardiovascular drugs, antibiotics, antidepressants, and pain relievers. It also segments by formulation types including oral tablets, capsules and syrups, extended release, and injectables, and by distribution channels including hospital pharmacies, retail pharmacies, online drugstores, and clinics. For the Myanmar generic drug manufacturing market, this kind of segmentation helps frame where local manufacturers might focus first: dosage forms that align with local packaging capabilities and distribution realities, while planning for more complex forms such as injectables that can demand stronger sterilization, filling, and packaging control. Import substitution in 2026, therefore, is best viewed as a system challenge across formulation, packaging inputs, and traceability, not a single factory decision.
What number best captures Myanmar’s consumer health demand context for local pharma production?
Why does packaging matter so much for import substitution in Myanmar pharmaceuticals?
How does IndexBox describe the value chain relevant to pharma-related chemical products in Myanmar?
How can serialization support local producers competing with imports?
What does the Myanmar generic drug manufacturing market discussion in 2026 depend on beyond formulation?